
Payactiv
- Rating
- 4.4
- Downloads
- 1.00M
- Content Rating
- Everyone
Payactiv - Screenshots
Pros
- Early access to earned wages can help cover unexpected expenses.
- Supports bill payments and money transfers from the app.
- Includes budgeting tools to help track spending and income.
- May offer discounts and financial wellness resources to members.
- Available through participating employers without a traditional credit check.
Cons
- Access depends on whether your employer supports Payactiv.
- Some services may include transaction or expedited-transfer fees.
- Not all features are available in every state or employer plan.
- Frequent wage advances can make the next paycheck feel smaller.
- Account setup may require employer and payroll information.
Payactiv - Description
- App Name
- Payactiv
- Package Name
- com.ProActMobile
- Developer
- On-demand pay and beyond
- Category
- Finance
- Last Updated
- Jun 4, 2014
- Version
- 2.2.8
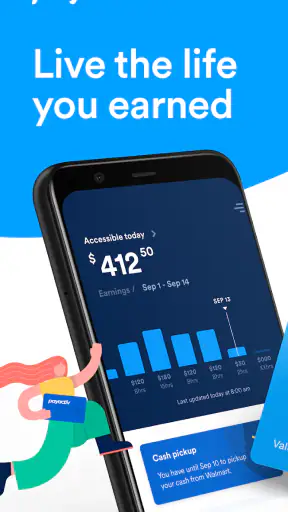
Payactiv is a finance app I would describe as a practical pressure-release tool rather than a complete money-management system. Its main idea is simple: help eligible workers access wages they have already earned before the normal payday, while also supporting broader financial-wellness goals. That can be genuinely useful when a small timing problem threatens to become an expensive one. It can also feel less impressive once the initial relief wears off, because early wage access works best as a carefully controlled exception, not as a permanent replacement for budgeting.
I spent time looking at where the app fits into everyday money habits, what makes it worth keeping, and where the experience can create friction. Payactiv is free, aimed at Everyone, and belongs to the Finance category. It was developed by On-demand pay and beyond, and its current version is 2.2.8. The app has built a substantial audience, with more than a million installs, an average rating of 4.4, and roughly forty-five thousand ratings alongside about nine thousand reviews. Those figures suggest that the central problem it addresses is familiar to many people, but popularity alone does not make early access a good choice for every budget.
What Payactiv Feels Like After the First Week
The first appeal is easy to understand. If I have already worked the hours but payday is still several days away, being able to reach part of those earnings can be more useful than taking out a conventional short-term loan. The important distinction is that this is connected to earned wages, not presented as extra income. That framing changes how I would use it: the app makes sense for smoothing a temporary gap, not for creating spending power that my regular paycheck cannot support.
A realistic example would be a midweek car repair, a utility bill that arrives earlier than expected, or groceries needed before a scheduled payday. In that situation, I would first check whether the expense is truly urgent and whether I can cover it without touching the money needed for rent, food, or other fixed commitments. If early access prevents a late fee or keeps a necessary expense from becoming a larger problem, the convenience has a clear purpose. If it simply allows me to buy something sooner, the same convenience can quietly move my financial stress forward.
The first-week experience is therefore less about discovering a long list of features and more about understanding the app's role. I would not install it expecting a full replacement for a bank account, a detailed investment service, or a sophisticated budgeting platform. Its strongest identity is narrower: it can help connect work already completed with a financial need happening before the regular pay cycle catches up.
That narrow focus is also a strength. Many financial apps ask users to build elaborate routines, categorize every purchase, or move accounts around. Payactiv can be easier to understand because its central question is more immediate: do I need access to earned pay before the usual date? For someone dealing with irregular expenses or a paycheck schedule that does not match real-life bills, that clarity can make the app feel useful quickly.
The decision that matters more than the download
Before relying on it, I would make sure I understand how the app connects to my employment and what amount is actually available to me. Access to an app does not automatically mean every worker can use every function in the same way. The practical value depends on eligibility and on whether the workplace and payroll arrangement support the service. That is the first question I would settle, because it determines whether Payactiv is a working part of my pay routine or merely an interesting download.
I would also treat the first successful use as a test rather than an invitation to withdraw repeatedly. The best early experiment is a small, planned need with a clear repayment, or paycheck-adjustment, consequence in mind. I would record what I accessed and then check the following pay cycle to see how the earlier withdrawal affected the amount arriving normally. That simple habit prevents the app from becoming psychologically invisible.
Another useful first-week habit is to separate emergencies from convenience. I would make two mental categories: expenses that protect essentials, and expenses that could wait. Payactiv is much easier to judge when it is used for the first category. The moment it starts funding routine extras, the app may feel helpful while making the next payday tighter.
Where it differs from the usual alternatives
The usual alternative is waiting for payday, using an overdraft facility, borrowing from someone close, putting the expense on a credit card, or applying for a short-term loan. Each option carries a different kind of cost. Waiting is cheapest when it is possible, but it does not solve a time-sensitive problem. Credit cards preserve cash flow but can turn a small purchase into revolving debt. Short-term borrowing may be faster in some cases, yet it can introduce a more serious repayment burden.
Payactiv's appeal is that it focuses on timing rather than asking me to borrow an entirely new amount. That does not make it free money or remove the need for discipline. It simply makes the relationship between work completed and money received more flexible. For a worker whose main problem is the gap between those two events, this can be a better fit than a general credit product.
On the other hand, someone who wants detailed spending analysis, long-term savings automation, investment tools, or a broad account dashboard may prefer a traditional personal-finance app or a bank's own tools. Payactiv should not be judged harshly for not being something else, but I would not keep it installed as my only financial app if my goal were comprehensive money management.
Why the Value Can Continue Beyond the First Month
The app earns lasting space on my phone only if it solves a recurring timing problem without becoming a recurring dependency. That is the central trade-off. A single early-access transaction can be valuable, but the long-term test is whether the service helps me handle pay cycles more calmly or merely makes it easier to spend before payday.
For workers with variable hours or expenses that arrive unevenly, the month-to-month value can be meaningful. A normal budget often assumes that income and bills line up neatly. Real life rarely does. A payment may be due before a paycheck, or an unexpected essential cost may appear during the quiet part of the pay cycle. In those cases, having a controlled way to access earned wages can reduce the temptation to use more expensive forms of credit.
I would use the app as part of a monthly plan, not as an automatic bridge every week. At the beginning of each pay period, I would note fixed bills and leave enough of the expected paycheck untouched for them. If I needed early access, I would write down the reason and the amount before requesting it. At the end of the month, I would review whether the withdrawal solved a genuine mismatch or simply covered spending that should have been postponed.
This turns Payactiv from a reflex into a decision point. That distinction matters because convenience can hide repetition. If I use it once for an unusual expense, it is a useful safety valve. If I use it every pay cycle for groceries, entertainment, or ordinary bills, the underlying budget may be too tight. In that situation, the app is showing me a problem rather than fixing it.
Financial wellness needs a personal definition
The phrase financial wellness can sound broad, but I would interpret it in a very practical way here. For me, wellness means knowing what will arrive on payday, keeping essential bills protected, and avoiding decisions made in panic. Early wage access can support that goal when it prevents a minor timing issue from becoming an overdraft or a high-cost borrowing problem.
It cannot replace the slower work of building a buffer, reducing recurring expenses, or changing an income problem. That is an important limitation to keep in view. If my monthly income is consistently lower than my necessary costs, accessing wages sooner only rearranges the pressure. The app may make the current week easier while leaving the next payday more difficult.
One non-obvious benefit is that the app can act as a diagnostic tool. If I notice that I repeatedly need early access at the same point in every month, I can identify the bill or spending pattern causing the gap. The useful outcome may not be another withdrawal; it may be moving a payment date, changing a subscription, building a small reserve, or asking an employer about pay-cycle options. Used thoughtfully, the app can reveal the shape of a cash-flow problem.
What I would monitor from month to month
I would pay attention to three things: the reason for each use, the effect on the next regular paycheck, and whether the service is changing my spending behavior. The first shows whether access is necessary. The second shows the real cost in cash-flow terms. The third is the most important for long-term value, because an app that reduces short-term anxiety but increases habitual overspending is not improving my finances.
I would also keep a separate emergency reserve whenever possible. Relying on early wages as the only backup leaves no protection for a second problem arriving before the next pay cycle. Even a modest reserve gives me another choice and makes it easier to use Payactiv selectively rather than automatically.
There is a useful psychological rule here: I would avoid treating the available amount as a balance that belongs to me today. I would treat it as part of a future paycheck that has been moved forward. That mental label makes the later reduction more visible and helps prevent the app from feeling like an expandable spending account.
Maintenance, Friction, and the Habits It Demands
Payactiv is not a set-and-forget solution. Its maintenance burden is not necessarily technical; it is mostly financial awareness. I need to remember what I accessed, why I accessed it, and what the next paycheck must cover. That is manageable for a disciplined user, but it can become tiring for someone already struggling to track money.
The app is most comfortable when my employment and pay information remain current and the service continues to fit my workplace arrangement. Any change in job, payroll setup, hours, or pay schedule can affect how useful the app is. I would therefore revisit the setup after a job change instead of assuming that the same experience will continue unchanged.
Another source of friction is the need to understand the difference between availability and affordability. Seeing that earned pay can be accessed does not mean I can safely take all of it early. I would check the upcoming bills first, then decide whether the amount I need leaves enough room for essentials. This extra step is easy to skip when money is tight, which is why the app rewards users who create their own rules.
My preferred rule would be to use early access only for a named expense, never simply because funds are visible. I would also avoid making a request while emotional or rushed. Writing down the expense takes less than a minute, but it creates a pause between the financial problem and the action. That pause is one of the most valuable safeguards I can add to the experience.
Where fatigue starts to appear
The novelty fades when the app becomes associated with the same shortfall over and over. At first, early access can feel like control. Later, repeated use can feel like managing a paycheck that is permanently out of sync. The service may still be functioning as intended, but the emotional experience changes because I am no longer solving an unusual gap; I am maintaining a cycle.
There is also a risk of fragmented attention. If I use Payactiv alongside a bank app, a budgeting app, credit accounts, and payment reminders, I may have several places showing different pieces of my financial picture. The app is helpful for its specific purpose, but it does not remove the need for one reliable overview of total cash flow. I would choose one primary place to track bills and use Payactiv as a supporting tool.
Another fatigue point is uncertainty around personal eligibility or access. The service's usefulness is tied to the employment and payroll context behind it, so a user should not assume that installing the app guarantees a permanent, identical experience. I would consider that dependence before making it part of an essential emergency plan. A backup option, such as savings or a clearly understood bank facility, is still sensible.
For users who dislike financial administration, the app may create more mental work than expected. It can reduce the stress of one immediate payment while adding a later reminder to account for the reduced paycheck. That trade-off is worthwhile when the alternative is more expensive or damaging, but not when the expense could simply wait.
Who should keep it and who should skip it
I would recommend keeping Payactiv if I am paid through a supported work arrangement, occasionally face a gap before payday, and can commit to tracking each early-access decision. It is particularly relevant when the problem is timing rather than a permanent shortage. In that situation, the app can be a useful layer between ordinary income and unexpected essentials.
I would be cautious if I already use most of each paycheck before it arrives. Early access may provide relief, but it can also make the next cycle harder. I would also look elsewhere if my main goal is investing, detailed budgeting, bill negotiation, credit building, or a complete banking relationship. A bank account, savings system, or dedicated budgeting tool is likely to serve those needs more directly.
I would skip it as a first choice for discretionary spending. The fact that wages have been earned does not make every purchase wise, and the app's convenience can remove the natural pause created by waiting for payday. If waiting is uncomfortable but safe, waiting is often the better financial decision.
My Long-Term Verdict on Payactiv
After the initial appeal fades, Payactiv still has a legitimate reason to remain installed, but only for a specific kind of user. I see it as a targeted cash-flow tool: valuable when earned wages and urgent expenses fall on opposite sides of the pay calendar, less valuable when used to cover an ongoing budget deficit or ordinary wants.
The free price makes it easy to try, and the Everyone age rating keeps the product broadly approachable. Its established presence, including an average rating of 4.4 from around forty-five thousand ratings, gives me some confidence that it addresses a real and recurring need. Still, those figures do not replace personal testing. The meaningful question is whether it works with my employment situation and whether I can use it without weakening the next payday.
My strongest recommendation is to create a personal usage policy before the first withdrawal. I would define what counts as an emergency, protect fixed bills, record every use, and review the following paycheck. I would also set a point at which repeated use becomes a signal to change the budget rather than request more early access. Those rules turn a convenient feature into a controlled financial habit.
Payactiv earns lasting space when it reduces expensive timing problems without becoming part of the problem. I would recommend it to someone who needs occasional flexibility and understands that early wages are still future income. I would not recommend relying on it as a permanent substitute for savings, a realistic budget, or a broader financial plan. Its long-term value comes from restraint: used selectively, it can make an awkward pay cycle easier; used automatically, it can make financial fatigue harder to escape.
For that reason, I would keep it available as a backup rather than build my entire money routine around it. That feels like the fairest way to use this particular Finance app: appreciate the immediate help, learn from the cash-flow pattern it reveals, and keep working toward a situation where I need early access less often.
FAQ
What is Payactiv, and how does it work?
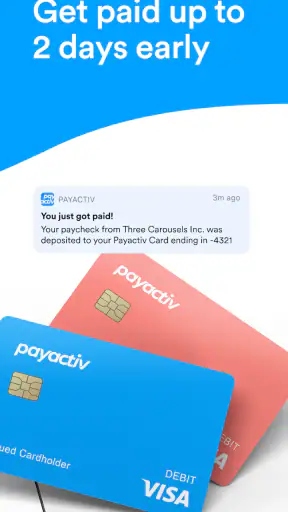
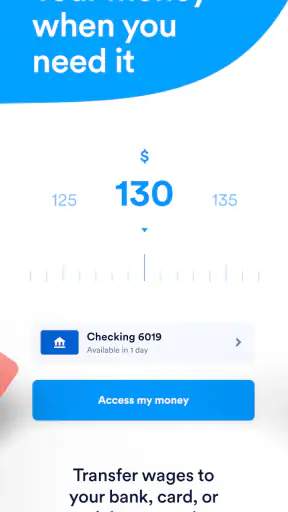
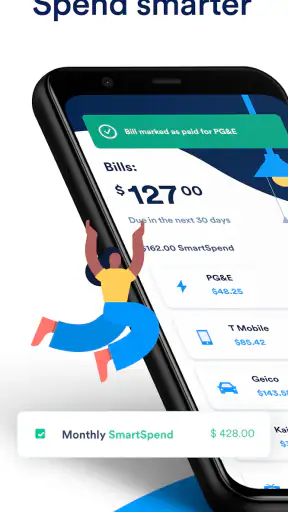
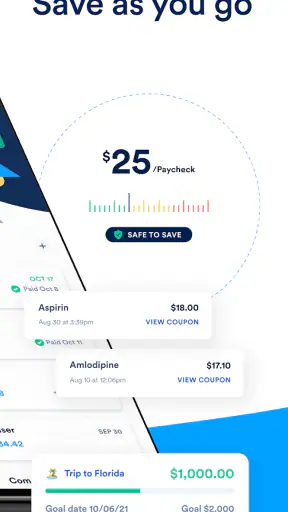
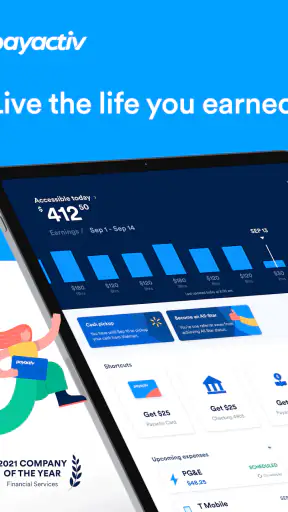
Payactiv is a financial wellness app that may allow eligible employees to access part of their earned wages before the regular payday. After your employer connects its payroll system with Payactiv, the app can show available earned income and let you request a transfer, depending on your employer’s rules and your work history. It may also include budgeting tools, bill-payment options, savings features, and access to a Payactiv card.
Who can use Payactiv, and does my employer need to participate?
Payactiv is generally intended for employees whose employers offer the service through an approved payroll or benefits partnership. Downloading the app alone does not guarantee access to earned-wage features. During registration, you may need to verify your identity and employment details, and availability can depend on your employer, payroll provider, location, pay cycle, and other eligibility requirements. Check with your employer if you cannot enroll.
How quickly can I receive money through Payactiv?
Transfer speed depends on the delivery method you select and the terms available through your employer and Payactiv account. Some users may receive funds quickly through an eligible debit card or supported instant-transfer option, while standard bank transfers can take longer, especially on weekends or holidays. Before confirming a transaction, review the displayed arrival time, limits, and any applicable fee.
Does Payactiv charge fees for accessing earned wages?
Payactiv’s costs can vary according to your employer’s arrangement, the transfer method, and the specific services you use. Certain options may be free, while expedited transfers, card-related services, bill payments, or other features may involve charges. The app normally presents applicable pricing before you complete an action, so review the confirmation screen carefully rather than assuming every withdrawal or service is free.
Is Payactiv safe to use, and what information does it require?
Payactiv uses account verification and security measures intended to protect personal and financial information, but users should still follow normal precautions such as creating a strong password, enabling available security features, and avoiding suspicious links. The app may request identity, employment, bank, or card details to provide its services. Read the privacy policy and permissions carefully, and contact official support if anything appears unusual.


